













ISO 20022 and ISO 8583 solve two different problems. ISO 8583 is the messaging standard behind every card swipe and ATM withdrawal. ISO 20022 is the standard now carrying nearly all cross-border and high-value payment instructions worldwide — and as of November 2025, that migration is no longer a future event. It already happened.
If your team is still working out what this means for your payments stack, here’s the short version: ISO 8583 isn’t going anywhere for card rails, but every high-value and cross-border payment message your organization sends or receives now has to speak ISO 20022’s structured, XML-based language. Below is what changed, what’s still ahead, and how to tell which standard governs which part of your environment.
What is ISO 8583 vs. ISO 20022, at a glance
Two standards, two very different jobs.
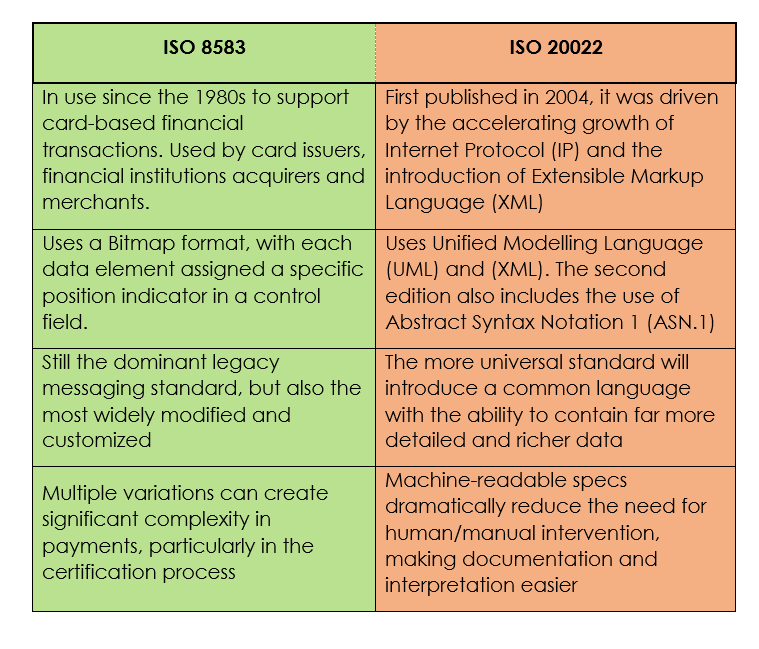
ISO 8583 answers one question: how do you move funds when a cardholder is present? ISO 20022 answers a much bigger one: how does every financial institution, market infrastructure, and corporate treasury describe a payment the same way, regardless of country, currency, or system?
They were never meant to compete. Before ISO 20022 existed, corporate and high-value payments ran on SWIFT’s older MT message formats, and retail card payments ran on ISO 8583 — with almost no shared structure between the two. ISO 20022 was built to bring the fragmented side of that world (corporate, cross-border, high-value) into one common, machine-readable format. It was never designed to replace ISO 8583 on the card side.
| ISO 8583 | ISO 20022 | |
|---|---|---|
| Scope | Card-based financial transactions only | All payment types — high-value, cross-border, real-time, securities, FX |
| Format | Bitmap, fixed and variable-length fields | XML, UML-modeled, ASN.1 |
| Primary users | Card networks, acquirers, issuers, POS and ATM operators | Central banks, correspondent banks, RTGS operators, corporates |
| Data richness | Limited, network-specific fields | Up to 10x more structured data per message |
| Status in 2026 | Still the dominant standard for retail card payments | Mandatory for SWIFT cross-border traffic; expanding into domestic and RTGS rails |
The table above is the fast answer. The rest of this guide covers why each standard exists, what changed in November 2025, and what to check before you assume either one is “done” in your environment.
What is ISO 8583?
The standard behind every card swipe.
ISO 8583, officially titled Financial Transaction Card-Originated Messages — Interchange Message Specifications, is the messaging protocol for transactions initiated with a payment card. When a cardholder taps, swipes, or inserts a card, the transaction data moves through the network using ISO 8583 data elements, message types, and code values.
It's been the backbone of card payments since the 1980s, and it still is. Visa, Mastercard, and most acquirers and issuers base their authorization messages on it. ISO 8583 uses a bitmap format, assigning each data element a fixed position in a control field, and it defines point-to-point messages for network sign-on, sign-off, and totals reconciliation as well as the transaction itself. A single message can carry purchases, withdrawals, deposits, reversals, refunds, balance inquiries, and inter-account transfers.
For a full breakdown of message structure, bitmaps, and Message Type Indicators, see our guide to ISO 8583.
What is ISO 20022?
One data dictionary for every payment message.
ISO 20022 is a common, structured messaging framework that lets payment, securities, FX, and trade data move between institutions in a shared format — instead of dozens of regional and legacy variants that don't talk to each other. Messages are built using Unified Modeling Language (UML), Extensible Markup Language (XML), and Abstract Syntax Notation One (ASN.1).
The practical difference is data volume. Where a legacy SWIFT MT message might carry a payer name and a reference code, an ISO 20022 message can carry the full payer and beneficiary address, structured remittance information, and a much larger character set — roughly ten times the field capacity of the format it replaces. That matters directly for compliance and fraud teams, because sanctions screening and AML checks are only as good as the data attached to the payment.
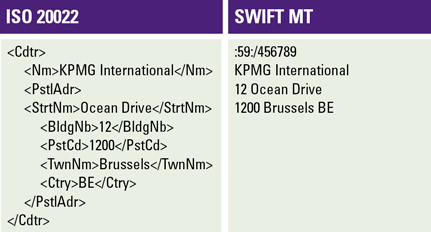
“ISO 20022 standardizes common data objects from the various market infrastructures and offers a common terminology for every financial institution.” — Compact
ISO 20022 is an open standard — free to use, and built to be extended by whoever adopts it, which is part of why it's been adopted well beyond SWIFT's own network.
Read more in our guide, What is ISO 20022 and how is it changing?
Where ISO 20022 adoption actually stands in 2026
The coexistence period is over. Here's what that means.
For years, ISO 20022 adoption was framed as something coming. It's not anymore. SWIFT's coexistence period, which let banks send either the legacy MT format or the new ISO 20022 MX format for cross-border payments, ended on November 22, 2025. As of that date, cross-border payment instructions on the SWIFT network are exchanged in ISO 20022 by default.
In the run-up to the deadline, SWIFT reported that more than 75% of payment instruction traffic had already shifted to ISO 20022 messages, with thousands of institutions sending and receiving MX messages across more than 200 countries. That's a real migration, not a projection.
The next milestone is already on the calendar: from November 2025, SWIFT introduced a transitional hybrid address format requiring structured town name and country code fields, ahead of a harder deadline in November 2026, when fully unstructured postal addresses will no longer be accepted in CBPR+ cross-border messages. If your organization hasn't mapped its address data to the structured format yet, that's the deadline to work backward from now.
The images below on adoption timelines and country counts were published while the migration was still in progress — useful for the shape of the rollout, but treat any specific date or percentage in them as historical context rather than the current state, which is described above.
Why the shift matters beyond payments
ISO 20022 was never only a payments project. It's becoming the shared messaging layer across securities, trade services, FX, and card-adjacent services, because every one of those domains benefits from the same structured, interoperable data model. A few of the concrete gains:
-
Richer, more useful data: up to ten times more information per message, which feeds directly into better fraud detection and sanctions screening.
-
Higher straight-through processing rates: fewer exceptions and manual interventions because the data arrives correctly structured the first time.
-
Better reconciliation: consistent, standardized fields make matching payments to invoices and ledger entries far less manual.
-
Support for non-Latin character sets: a character set roughly ten times larger than legacy MT messages, which matters directly for adoption in markets like China and the Middle East.
-
Genuine interoperability: formats that previously couldn't work together — different regional RTGS systems, for example — now share a common structure.
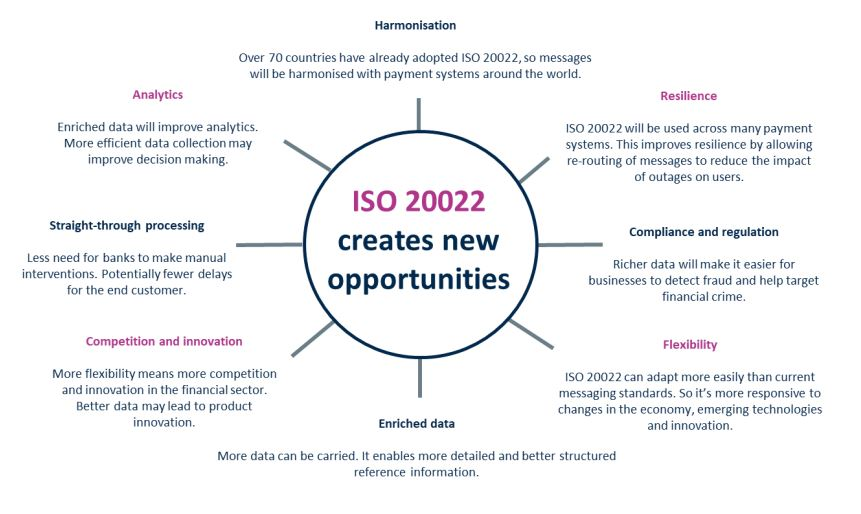
Image source: Bank of England
Do you still need ISO 8583? A quick decision framework
Yes — for card rails. Here's how to know where each standard applies.
The most common mistake teams make when the ISO 20022 migration hits the news cycle is assuming it replaces ISO 8583 everywhere. It doesn't. Use this as a quick gut-check for your own environment:
-
Card-present and card-not-present transactions (POS, ATM, e-commerce card checkout): still ISO 8583. Visa and Mastercard authorization networks haven't moved off it, and there's no scheduled retirement date.
-
Cross-border wire and correspondent banking payments: ISO 20022 (MX), as of November 2025.
-
High-value and RTGS payments: ISO 20022, with most major real-time gross settlement systems having completed or well underway with their own migrations. Read more in our guide to RTGS for high-value payments.
-
Domestic ACH and batch payments: varies by market — some domestic rails have adopted ISO 20022, others still run legacy formats. Check with your local scheme operator rather than assuming.
-
New card scheme initiatives: some card networks are exploring ISO 20022 for specific use cases, but this is early and scheme-specific — not a wholesale replacement of ISO 8583.
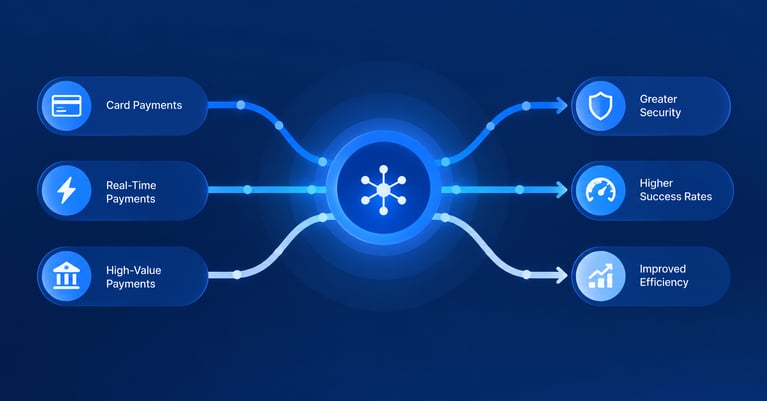
If your organization touches more than one of these categories — which most acquirers, processors, and banks do — you're not choosing one standard over the other. You're running both, which means your monitoring and reconciliation tooling needs to understand both message formats natively, not just the one that's newer.
Where ISO 8583 still holds up — and where it doesn't
Multiple versions of the same standard create real complexity.
ISO 8583 remains a well-understood, purpose-built standard for card transactions, and it isn't going away. But it has one structural weakness that ISO 20022 was designed to fix: fragmentation. Because ISO 8583 has been implemented with multiple variations across networks and regions, certification and interpretation of the standard often still requires manual documentation and human sign-off.
ISO 20022, by contrast, is machine-readable by design, which is a large part of why it's been prioritized for cross-border and high-value rails first — those are exactly the payment types where certification complexity and manual intervention are most expensive.
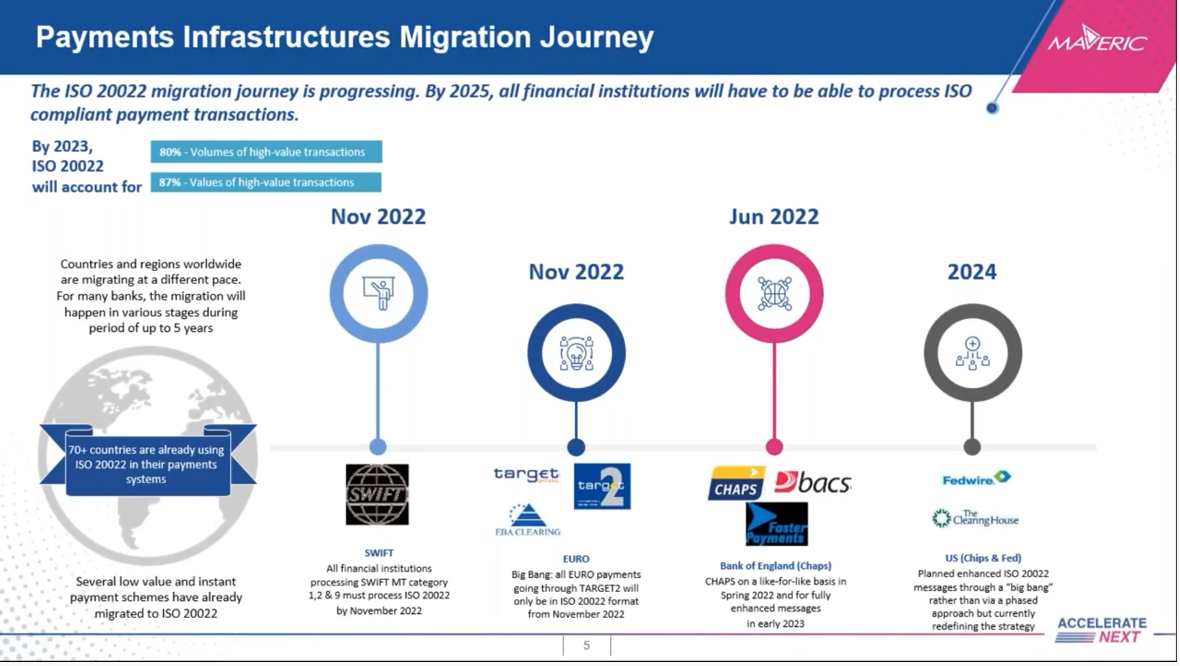
Image source: Temenos payments hub (webinar)
How IR Transact helps you monitor both standards
One less thing to reconcile manually.
Running ISO 8583 and ISO 20022 side by side means your monitoring has to speak both languages — and catch problems in either one before they become customer-facing incidents or compliance exposure.
IR Transact, powered by Prognosis, gives payments teams real-time visibility across high-value, cross-border, and card payment environments — without needing separate tooling for legacy and ISO 20022-native message formats. It helps you:
-
See transaction health in real time, across settlement queues, balance thresholds, and flagged accounts, regardless of which messaging standard the payment arrived on.
-
Investigate faster, with detailed historical transaction data that lets your team trace the root cause of a failed or delayed payment instead of guessing.
-
Reduce reconciliation overhead, as ISO 20022's richer data structure feeds directly into more accurate, automated matching.
Real-time payments analytics matter more, not less, now that the ISO 20022 migration has moved from planning to production — and if your team is still evaluating how a modern payments monitoring layer should fit together, our guide on evaluating and choosing a payments hub is a useful next read.
FAQ
Quick answers to the questions we hear most.
Is ISO 8583 being replaced by ISO 20022?
Not for card payments. ISO 20022 has replaced legacy SWIFT MT formats for cross-border and high-value payments, but card networks like Visa and Mastercard still run on ISO 8583, with no announced retirement date.
Has the SWIFT ISO 20022 migration actually finished?
The formal coexistence period ended on November 22, 2025, meaning cross-border payment instructions are now exchanged in ISO 20022 by default. A further deadline in November 2026 will remove support for unstructured postal addresses in CBPR+ messages, so some transition work is still ahead for institutions that haven't completed address-data mapping.
What's the main practical difference between ISO 20022 and ISO 8583?
ISO 8583 uses a bitmap format built specifically for card transactions, with limited, network-specific data fields. ISO 20022 uses XML and carries far richer, structured data — supporting detailed remittance information, longer references, and non-Latin character sets — across every payment type, not just cards.
Does ISO 20022 affect card payments at all?
Not directly for authorization messaging today, which still runs on ISO 8583. Some card networks are exploring ISO 20022 for specific adjacent use cases, but this is early-stage and scheme-specific rather than a broad replacement.
Can ISO 8583 and ISO 20022 coexist long-term?
Yes. They cover different transaction types — card-originated versus cross-border, high-value, and market-infrastructure payments — and there's no technical or regulatory driver pushing card networks to migrate wholesale. Most payments organizations should plan to run monitoring and reconciliation across both standards indefinitely, not for a one-time switchover.