













Where UC&C becomes mission critical
Banking, finance and insurance organizations have made unified communications the front line of the customer relationship — and service assurance hasn't kept pace.
For banks, insurers and securities firms, unified communications & collaboration (UC&C) is no longer back-office infrastructure — it's where advice is given, transactions are confirmed and disputes are resolved. That shift changes what "service assurance" has to mean: not just keeping a platform online, but proving, in a heavily regulated environment, that every customer interaction was available, high-quality, and recorded.
Creation of digital experiences is accelerating
Communication is being built into the applications people already use, not bolted on afterward.
By 2022, a third of organizations were already integrating core business applications — CRM, ERP — directly into video collaboration via APIs or communications platform as a service (CPaaS). That kind of integration is now table stakes: organizations increasingly treat it as a baseline requirement, not a differentiator.
Increased spending on UC&C
Spend is following the workload — and it isn't evenly distributed by region.
By 2027, organizations will be spending over $80 billion on UC&C systems and services. Latin America (11.2%) and APJ (10.0%) are forecast to post higher CAGRs over the 2021–2026 period than EMEA (7.8%) or even the United States, as adoption momentum builds in regions that previously lagged the US and EMEA.
Cloud as the main driver
Hybrid deployment, not full migration, is the model financial services is actually adopting.
There is significant demand for hybrid UC implementations, much of it driven by extending consistent, always-on communications and collaboration from internal teams out to customer interactions. About 38% of enterprise UC&C implementations were on UCaaS in 2022 — a share expected to keep climbing as hybrid cloud adoption in financial services increases.
Organizations are enhancing their UC&C capabilities
AI investment and network performance investment are rising together — not as separate line items.
About 45% of organizations are increasing investment in new capabilities such as AI/ML that improve the employee and customer experience of integrated UC. Investment in network performance management systems is expected to grow at a CAGR of 5.2% through 2026.
Four foundational pillars of the future
These four hold regardless of vendor, region, or deployment model.
Extreme availability
UC&C is mission critical. Services need to be available around the clock for customers, prospects, partners, vendors, and employees alike.
Choice of deployment options
A deployment model that supports cloud, hybrid, and on-premises platforms without forcing a single path.
Openness and compatibility
A complete view and control of multi-vendor UC&C environments, not just the vendor's own stack.
Transparency, visibility, and control
The ability to identify bottlenecks and drill into root cause analysis at a granular level.
Table of Contents
- Asia Pacific: User and customer experience more critical than ever
- Middle East & Africa: Customer focus critical amid digital growth
- Europe: User and customer experience more critical than ever
- Mission critical everywhere
- Emerging trends impacting UC&C management
- UC&C service assurance still has challenges
- Six components of UC&C performance management to deliver true business value to financial services
- Prospering amid new working realities of the post-pandemic business era
- About the IDC Analyst
Asia Pacific: User and customer experience more critical than ever
Asia Pacific is scaling UC&C fastest — and asking the most of it at the same time.
Financial organizations across the region have accelerated the way they operate to compete in a digital-first market. Digitalization and hybrid working are turning UC&C performance management from a nice-to-have into a business essential.
- IDC projected Asia Pacific UC&C vendor revenue would grow 9% to over $15 billion by 2024.
- IDC projected regional spend on unified communications as a service (UCaaS) and managed communication solutions would reach over $4.5 billion by 2024, as adoption of UCaaS or managed solutions continued to rise.
- In the Asia Pacific region, IDC projected the combined units/lines/licenses/seats for managed/hosted voice and UCaaS technology would grow 13% in 2024.
- Banking, financial services, and insurance (BFSI) organizations in Asia Pacific say the top technologies set to have a major impact on collaboration are Internet of Things (IoT) (48%) and automation (35%).
Regulations and compliance
Across the Asia Pacific region, regulators have laid down stringent procedures for data capture, privacy, trade surveillance, and timely detection and action on suspicious matters. Regulatory reporting and record-keeping requirements for customer-onboarding interactions have increased significantly since the pandemic.
Sheer rise in transactions and interactions
Digital adoption accelerated hard during the disruption of the early 2020s, and it hasn't reversed — financial services firms now need to proactively monitor every interaction to keep the customer experience consistent.
- AI improvements in areas such as call centers and collections are expected to drive a 25% increase in transaction volumes alongside an almost 10% reduction in servicing expenses.
- About 54% of the region's banks are investing in digital banking channels to improve customer experience.
- Customer experience transformation is the top business priority for 62% of banking and financial services institutions, as digital acceleration widens the competitive landscape and raises the bar for consistent, omni-channel interactions.
Impact to investments
Optimizing IT investment by keeping a close watch on cost-to-income ratios.
- About 63% of BFSI organizations in the region expect to increase planned spending on collaboration in 2024.
Data heavy
Gaining customer intelligence from actual real-time data, not assumptions about the customer.
- About 43% of banks in Asia Pacific (excluding Japan) are shifting toward a public-cloud technology architecture within the next 24 months, pushing more data into motion.
- Asia's financial services companies are prioritizing data modernization, big data and analytics (BDA), and AI initiatives to personalize the client experience — the top spending growth areas after security.
New customer focus delivered by distributed teams
Adopting a distributed operating model while keeping development and support consistent for the customer on the other end.
- About 76% of Asia Pacific BFSI organizations say employees work away from the physical office or worksite at least one day a week; 22% say employees are away more than half the week.
New modalities of customer interactions
Remote digital engagement — self-managed transactions, pre-staged interactions, co-browsing, consent-driven interactions, and advice- or recommendation-driven interactions.
- A third of Asia Pacific BFSI companies name enabling digital transformation as a top-three driver for investing in UC&C.
- About 86% of these companies say they use UC&C tools to collaborate directly with customers.
Middle East & Africa: Customer focus critical amid digital growth
In META, UC&C investment is being driven as much by platform strategy as by customer demand.
Like other parts of the world, accelerated digital usage has financial services organizations across the Middle East & Africa prioritizing UC&C for a consistent customer experience.
- About 61% of CIOs in the Middle East, Turkey and Africa (META) region say digitalizing operations is a key priority, and 40% say enabling hybrid work is a key priority.
- Financial services is projected to be the fastest-growing sector for digital spending in the region, with a CAGR of 18% through 2026 — RPA-based claims processing is the fastest-growing use case within it.
- Expect platform-led innovation across the region: spending on cloud-based data management and AI platforms is forecast to grow at a CAGR of 40% from 2021 through 2026.
- Customer-experience spending in Saudi Arabia, the UAE, and Qatar is concentrated in mobile apps and progressive web apps (57%), AI-based workflow automation (55%), and customer privacy and consent management (46%).
Regulations and compliance
Financial industry regulators across the Middle East and Africa (MEA) require digital record-keeping of all actual or intended transactions with customers, as well as inter-bank dealings. Digital record-keeping is also a core part of most banks' service charters.
Sheer rise in transactions and interactions
Digital adoption accelerated hard during the disruption of the early 2020s, and it hasn't reversed — financial services firms now need to proactively monitor every interaction to keep the customer experience consistent.
- About 44% of BFSI organizations in MEA are digitally transforming in-branch and physical customer experiences.
- 77% of Middle East financial institutions are focused on scaling customer experience on mobile and online platforms, and 63% are developing customer journeys using digital capabilities.
Data heavy
Gaining customer intelligence from actual real-time data, not assumptions about the customer.
- Investing in data excellence — developing data strategies, classification processes, and data-stewardship plans — is the top strategic IT capability named by Middle East financial organizations (58%).
- About 42% of Middle East BFSI organizations are significantly increasing investment in personalizing services and improving customer analytics using AI/ML.
Impact to investments
Optimizing IT investment by keeping a close watch on cost-to-income ratios.
- Finance organizations in the region are forecast to increase spending on collaborative applications at a CAGR of 16% between 2021 and 2026, as firms seek to become more resilient and agile — including incorporating AI into existing solutions to extend usability and value.
New customer focus delivered by distributed teams
Adopting a distributed operating model while keeping development and support consistent for the customer on the other end.
- Nearly half (44%) of Middle East financial institutions say enabling a long-term hybrid work model is one of their top three priorities.
New modalities of customer interactions
Remote digital engagement — self-managed transactions, pre-staged interactions, co-browsing, consent-driven interactions, and advice- or recommendation-driven interactions.
- Over 70% of BFSI organizations across the META region plan to invest in scaling up their digital platform experiences over the next 12–18 months.
Europe: User and customer experience more critical
Europe got to hybrid work and cloud communications before most industries had a choice in the matter — regulation made sure of it.
MiFID II record-keeping requirements mean European financial institutions have never been able to treat UC&C as a purely operational decision. Every deployment choice is also a compliance choice, which is part of why the region's cloud migration has been so deliberate.
- UC&C spending is forecast to grow at a CAGR of 6.2% from 2022–2027, driven mainly by growing adoption of cloud-based solutions to enable hybrid working.
- Almost 90% of European financial organizations use UC&C solutions, split roughly evenly between premises-based UC&C (29%), multitenant public-cloud UCaaS (27%), and single-instance private-cloud UCaaS (33%).
- About 56% of European financial organizations will either fully (18%) or partially (38%) replace on-prem UC with cloud-based or hybrid infrastructure within the next two years.
- Top priorities when implementing hybrid UC&C: capturing opex benefits of cloud (38%), minimizing full-migration risk (38%), improving scalability (31%), and enabling hybrid/remote work (25%).
Regulations and compliance
- Financial services firms are required to record all voice and electronic communications relating to actual or intended transactions.
- Data must be retained for at least five years (seven in certain cases), in a durable medium that regulators can access easily.
- Non-compliance with MiFID II carries fines of up to €5 million, or 10% of global turnover.
Sheer rise in transactions
- Digital adoption accelerated hard during the disruption of the early 2020s, and it hasn't reversed — financial services firms now need to proactively monitor every interaction to keep the customer experience consistent.
- 38% of European financial institutions currently use digital customer engagement channels; another 35% plan to within two years.
- About 26% of European consumers say they interact with their bank mostly digitally, and 6% say exclusively digitally.
Data heavy
- Gaining customer intelligence from actual real-time data, not assumptions about the customer.
- 27% of European financial institutions say connecting data for a 360-degree view of the customer journey is a top priority for driving CX in the contact center.
- A quarter of these institutions also name AI-based analytics as a top CX priority.
Impact to investments
- About 62% of European retail banks plan to increase IT spending to accelerate digital transformation.
- Around 34% of banks plan further investment in hybrid workplace and remote-working solutions.
- Data protection is the top ICT investment priority, likely reflecting the shift to remote work.
New customer focus delivered by distributed teams
- IDC projected that by 2024, more than 85% of customer banking interactions would be serviced through remote channels.
- 27% of European organizations place UC&C among their top three tech investment areas, alongside distributed-team enablement, cloud services, secure remote working, and network security.
- The top benefit cited for cloud-based collaboration tools is enabling remote content creation and work from anywhere — 60% of employees plan to work from home at least one day a week.
New modalities of customer interactions
- About 38% of European financial institutions use digital customer engagement channels such as web, self-service, messaging, or video; another 42% plan to within two years.
- 42% of European banks treat process digitalization tools — digital self-service, for example — as a CX priority. The shift to faster processing and contextual banking has made alerts, notifications, and mobile apps genuinely valued services, not just convenience features.
Mission critical everywhere
Across every region above, UC&C is now load-bearing for the business, not supporting infrastructure.
Across many segments of financial services, UC&C is now central to delivering a new model of financial services.
-
Enabling new business models
Banks moving into advisory services — building new revenue models around recommendations, facilitation, and lifestyle platforms rather than interest income alone. -
Supporting Open Banking
Extending unified communications to Open Banking by exposing functionality, applications, and data to trusted third parties. -
Enterprise-wide insights
Standardizing data, insights, and actions across business units and silos, so the enterprise operates as one. -
New customer engagement models
Launching new modes of customer engagement — pre-staging, self-direction, collaboration, and proactive outreach. -
Empowering people
Institutionalizing new ways of working — automation, pre-staging, and intelligence — with collaboration at the core. -
Building a more agile business environment
Starting business agility with a new wave of intra-organization integration and collaboration — DevOps, DataOps, and risk-finance integration.
Emerging trends impacting UC&C management
The common thread across these ten trends: less manual intervention, more automated confidence.
As financial services organizations invest further in UC&C systems and services, having better control over the UC&C environment — and the user and customer experience it delivers — becomes critical.
-
Integration of business processes and applications remains crucial, with a continued focus on APIs, ecosystems, and IoT.
-
Hosted and cloud solutions keep growing, but hybrid environments remain the norm — security and data-privacy risk are the deciding factors for BFSI organizations.
-
Emphasis is shifting to use cases: customer experience, simplicity, and ease of use.
- Outdated equipment and dissatisfaction with legacy systems are driving demand for modernized UC&C.
- Lines of business now influence IT budgets and participate actively in technology decisions.
- Video integration and web real-time communication (WebRTC) remain prevalent in UC&C environments.
- Mobile and remote workers are driving demand, and true fixed-mobile convergence and mobile UCaaS are starting to emerge.
- Collaboration apps built with AI/ML capabilities are enabling new, more intelligent solutions that improve productivity and reshape the workplace. Generative AI use cases are nascent, but emerging fast.
- Migration from time division multiplexing (TDM) to VoIP continues, driven by cost savings, scalability, and support for hybrid working.
- The emphasis is shifting to solutions, not siloed products.
-
IDC projected that by 2024, 75% of enterprises would use cloud-based APIs to build customer-engagement applications that integrate UCaaS/CPaaS platforms with multichannel options to improve customer experience.
-
By 2026, 40% of enterprises are projected to double investment in hyperconnected digital spaces to increase productivity, improve collaboration, and boost energy efficiency.
- With GenAI as a catalyst, by 2027, 40% of enterprises are projected to rely on interwoven IT architectures across cloud, core data centers, and edge platforms to support dynamic, location-agnostic workflows.
- By 2027, the need for human operations intervention is projected to fall by 70%, as AI-enabled automation keeps digital infrastructure configuration, performance, cost, and security consistent — and improves service-level objectives (SLOs).
UC&C service assurance still has challenges
More UC&C investment doesn't automatically mean better visibility into it.
Banking, insurance, and securities investment organizations face a wide range of regulatory and operational challenges as they work toward better business and communications outcomes.
-
Real-time monitoring & alerting
Real-time visibility into each UC&C user's experience, with actionable performance information for faster issue resolution. -
End-to-end visibility
Real-time visibility, troubleshooting, and reporting across multi-vendor platform, network, and endpoint environments. -
Multiple vendors
The ability to manage complex workflows across multiple applications, devices, hybrid-cloud, and multi-vendor UC&C environments without added overhead. - Outside-in testing
Proactive testing of the UC&C environment to understand performance, availability, and quality before they affect the customer experience. - Regulatory compliance
Call recording to support quality management and meet compliance requirements. - Historical analytics
Historical analysis to improve user experience and inform management decisions.
Creating empowered financial services organizations
- Ensuring secure and scalable communications
The shift to remote and hybrid work pushed financial services firms to strengthen digital resilience, offering better remote support to employees and customers through secure, scalable communications and collaboration tools. - Empowering the contact center
Going digital doesn't remove the human touch. Improving contact center capabilities remains an ongoing priority for remote interactions and response times that protect client satisfaction. - Beyond the technology
The goal is business value: building the workplace of the future, integrating communications with applications, improving collaboration across lines of business, and addressing customer churn.
How IR Collaborate can help
The challenges above point to one requirement: real-time, multi-vendor visibility that a compliance team, a contact center lead, and a network engineer can all use.
IR Collaborate, powered by Prognosis, gives financial services organizations a single view across on-premises, cloud, and hybrid UC&C environments — including Avaya, Cisco Webex, Microsoft Teams, and Genesys deployments already in place. Teams get real-time visibility into call and session quality, root cause analysis across multi-vendor environments, and the historical reporting regulators expect, without having to replace the platforms already in production.
See how this applies to banking, insurance, and securities environments specifically on the IR Collaborate for Financial Services page, or explore the full IR Collaborate suite.
Six components of UC&C performance management to deliver true business value to financial services
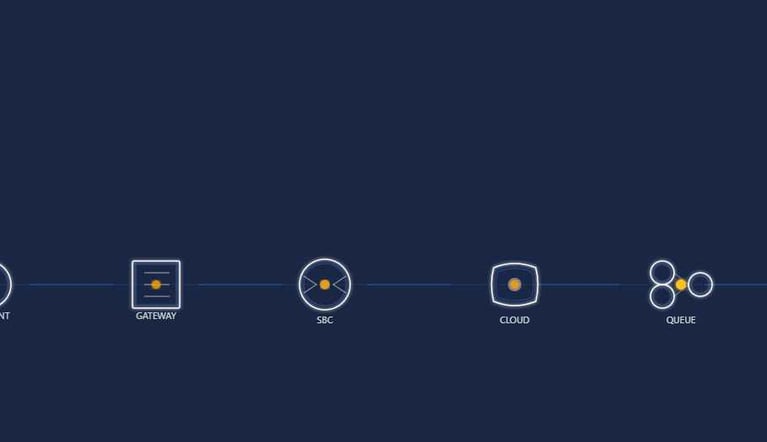
Read the framework below left to right — each stage builds on the one before it.
The six components map the full performance management lifecycle, from raw telemetry through to the reporting a compliance team can hand a regulator.

The overlap in the diagram below is the point: a change made for one audience — adding call recording for compliance, for example — usually pays off for the other two as well.

Prospering amid new working realities of the post-pandemic business era
Customer, employee, and regulator expectations have converged on the same requirement: prove it, don't just claim it.
Gaining visibility across UC&C helps organizations improve the customer experience, support employee engagement, and meet regulatory guidelines at the same time — it's rarely a trade-off between the three.
Customer
Customer-centricity is one of the top trends driving financial services organizations to find better, more reliable ways to interact with customers — including proactively testing and validating UC&C environments to catch issues before they reach the customer.
Employee
Work norms and culture keep changing, pushing financial services organizations to reevaluate business processes and support new levels of hybrid collaboration. With customer support and technology teams increasingly working from home part of the week, UC&C service assurance becomes more important, not less.
Regulator
Financial services remains heavily regulated because of its fiduciary responsibility and exposure to data theft and fraud. Beyond customer confidentiality, organizations are required to maintain records of all customer communications — to meet regulatory mandates and to support any legal remedies that follow.
Putting emerging technology to work
Optimizing the UC&C ecosystem to meet the expectations of customers, employees, and regulators at once.
- Microservices
Add flexibility to UC&C services - Cloud
Expand the UC&C ecosystem using cloud - Data insights
Collect and analyze data across the UC&C ecosystem - Expand intelligence
Get deep, real-time insight into UC&C user experience and call quality
About the IDC analyst
 Nikhil Batra
Research Director,
IDC Asia/Pacific
Nikhil Batra is a Research Director for the regional telecommunications team at IDC Asia/Pacific. Based in Australia, Nikhil focuses on telecom service provider and technology vendor strategies, along with enterprise services across the Asia/Pacific region. In his role, Nikhil produces intelligence reports and market insights for the regional telecom teams, and contributes to consulting projects for leading regional telcos and technology vendors.