












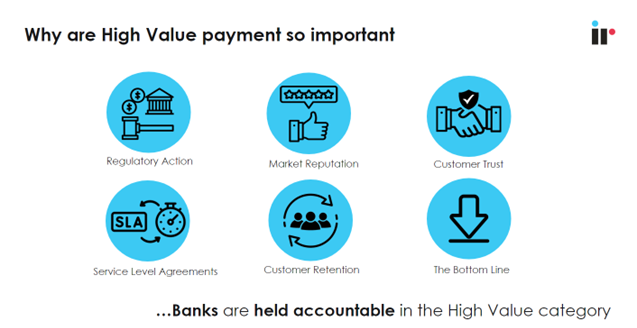
A single delayed settlement in a high-value payment system doesn't stay contained to one transaction. It can breach a regulator's cut-off window, trigger an SLA penalty, and put a bank's relationship with a counterparty at risk — all within minutes.
High-value payment systems move the wholesale and interbank sums that keep the global financial system running: large corporate settlements, FX transactions, and interbank transfers. Rising transaction volumes, tighter regulatory scrutiny, and growing multi-vendor complexity mean avoiding outright outages is no longer enough — banks need continuous visibility into how these systems are actually performing.
Effective monitoring means having real-time data on transaction response times, success rates, and error rates, plus the ability to spot the patterns that signal a problem before it escalates. That's not trivial across the layered, multi-jurisdiction complexity of domestic and international payment markets.
In a recent webinar, I shared practical guidance on monitoring the health of high-value payments — the tips are below, along with a closer look at why this matters more than ever.
Watch the webinar below
What are high-value payments?
The transactions too large, and too central, to leave unmonitored.
High-value payments are the wholesale and interbank transactions that run through a bank's treasury function — the central hub of payments globally. They cover large corporate settlements, interbank transfers, and FX flows, and are generally handled separately from retail and card payment rails.
Every market has its own name for this layer: Clearing House Automated Payment Systems (CHAPS) in the UK, Large-Value Payment Systems (LVPS) in the US, and High-Value Clearing Systems (HVCS) in Australia are three common examples — see our guide to mastering high-value payments for a fuller regional breakdown. Whatever the local name, these systems play the same role: moving large sums of money securely, efficiently, and in compliance with the rules of whichever jurisdiction they operate in.
Regulation and compliance
The cost of a compliance gap is rarely just the fine.
Banks operate high-value payment systems under strict, jurisdiction-specific regulation. In India, for example, the Reserve Bank of India oversees payment systems under the Payment and Settlement Systems Act, 2007 — and every market a bank operates in has its own equivalent framework, cut-off times, and reporting obligations.
Monitoring supports compliance in two ways: it can flag operational issues before they become settlement defaults or missed cut-off times, and it can surface suspicious transaction patterns for investigation and reporting to the relevant authority.
The consequences of getting this wrong compound quickly. A regulatory fine is rarely the only cost — a breached SLA can trigger customer penalties, and the reputational damage with counterparties, regulators, and ratings agencies can outlast the incident itself. Continuous monitoring is what turns compliance from a reactive scramble into a preventative discipline, and it also improves how quickly a bank can investigate and recover when something does go wrong.
Stability and resilience
Availability is the baseline. Recoverability is what regulators actually test for.
High-value payment systems have to stay available and perform as intended — a failure here doesn't just cost the bank operationally, it damages trust with the customers and counterparties depending on that transaction settling on time.
Monitoring helps surface the early signals of a developing failure — system overload, hardware or software degradation, network issues — before they cause an outage. Most jurisdictions also require annual audits of system resilience, along with documented disaster recovery and fallback procedures, as a condition of network membership. Monitoring data is part of the evidence base for that audit, not a separate exercise from it.
Legacy infrastructure
Too big to fail, and too big to replace.
Modern electronic payment systems date back to the 1970s, and the vendors who built the dominant platforms are nearly as old — particularly at larger banks. The technology is dated, but the scale of the business running on it makes a greenfield rebuild too risky to justify.
These platforms are upgraded regularly, but their core architecture wasn't designed to interface easily with modern systems — a constraint shared across major payment hub vendors. At scale, that makes them difficult to change, even as the underlying technology shows its age.
"Too big to replace, and too critical to leave unmonitored — that's the position most large payment hubs are in today."
Integrating with these traditional payment processing platforms is a specific area IR has invested in over a long track record — closing the gap between the core payments processing a hub provides and the operational need to monitor, troubleshoot, and analyze the transactions moving through it.
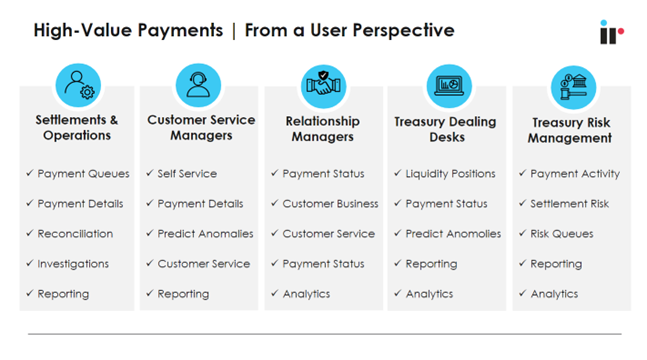
Why monitoring high-value payments is business-critical
Every one of these transactions is a target — for errors and for fraud.
Monitoring catches the errors and discrepancies that can occur mid-transaction — a payment routed to the wrong account, for instance, resulting in a delay or loss of funds. High-value payments are also a prime target for fraud, and monitoring can help detect fraudulent activity early, reducing potential exposure.
It also supports the compliance side directly — identifying the suspicious activity that may indicate money laundering or terrorist financing, and giving banks the evidence trail regulators expect to see. This depends on technology built to understand payment message structures and transaction flows specifically, so anomalies are flagged in context rather than as generic system alerts.
How IR Transact can help
Powered by Prognosis, built for payments specifically.
IR Transact's High Value Payments solution, part of the Prognosis platform, gives financial institutions real-time visibility into high-value payment queues and transaction flows — alongside the card and real-time payment streams IR Transact also monitors. It's built to:
- Flag anomalies as they happen:
Real-time monitoring of high-value payment queues and transaction status, so issues surface as they develop rather than after settlement. - Adapt to each institution's risk posture:
Custom thresholds, rules, and alerts configured to a bank's specific compliance requirements and risk appetite, rather than a one-size-fits-all default.
That combination gives payments and compliance teams one system that reflects how their environment actually needs to be watched — not a generic monitoring layer retrofitted onto a payments use case.
Seeing what's happening the moment it happens, rather than reconstructing it after the fact, is the difference between managing operational risk and being managed by it.
Want the full picture? Watch the webinar, or request a demo to see IR Transact monitor high-value payments in your environment.