











Cross-border eCommerce has already happened for most businesses — whether they planned for it or not. The harder problem is what comes next: getting paid the way each customer actually expects to pay.
Offering the local payment methods your customers expect, wherever they're located, has become a growth lever, not a nice-to-have. Get it wrong, and you're not just losing a sale — you're handing the customer to a competitor who got checkout right.
The customer-driven economy
Payment preference is now a competitive differentiator, not a back-office setting.
Customer expectations, not vendors, set the pace in payments today. Shoppers want to pay how they want to pay, with as few extra steps as possible between "add to cart" and "order confirmed." But the methods they prefer today won't necessarily be the ones they prefer next year.
As new ways to pay emerge and gain ground across different regions, businesses need to track payment trends continuously and revisit their payment strategy on a regular cycle — not set it once and leave it.
This means having visibility into:
- Where your customers live and transact
- How they buy (online, mobile, in person)
- What they're buying and how often
- What payment methods they're using
Different global payment preferences
Card networks still matter — but digital wallets are now the default in most of the world.
Payment preference varies enormously by country, and building a strategy that accounts for that difference takes real planning and resources.
According to Worldpay's 2026 Global Payments Report, digital wallets accounted for 56% of global eCommerce spend in 2025 — more than credit cards (20%), debit cards (10%), account-to-account transfers (7%) and buy now, pay later (BNPL) combined (4%). Card networks remain essential everywhere, but in most markets they're no longer the default checkout choice.
The regional picture is even more specific. In China, mobile wallets built into everyday super-apps are the default way to pay online. In India, real-time transfers processed through the Unified Payments Interface (UPI) dominate. In the US, credit and debit cards still lead at the point of sale, even as wallets take a growing share online. Across Europe, contactless card payments remain the norm in-store, with local wallet and bank-transfer schemes filling the gap online.
Given this level of regional variation, businesses of any size need a payment acceptance approach tailored to each country they sell into, not a single global default. Our guide to the digital payment lifecycle breaks down how each of these methods actually moves money, if you want the mechanics behind the preference.
Below are some of the preferred payment methods by country:
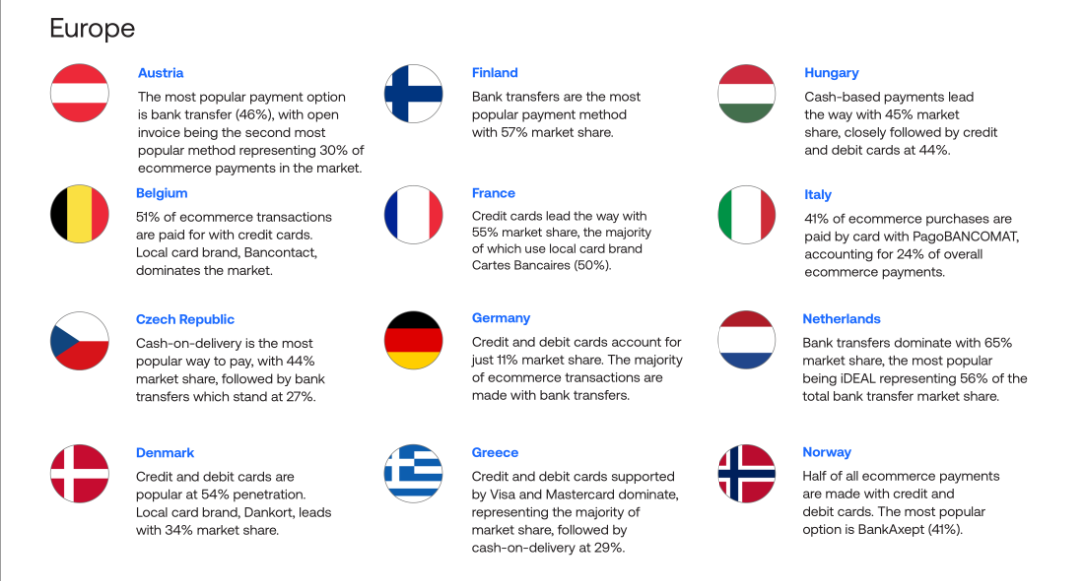
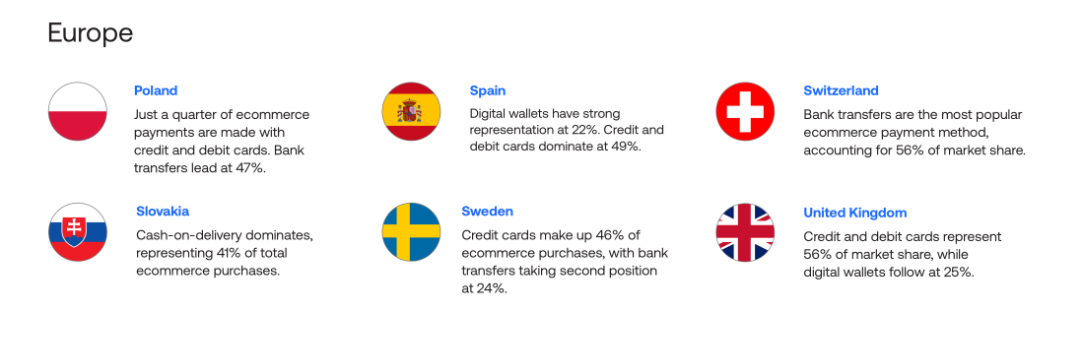
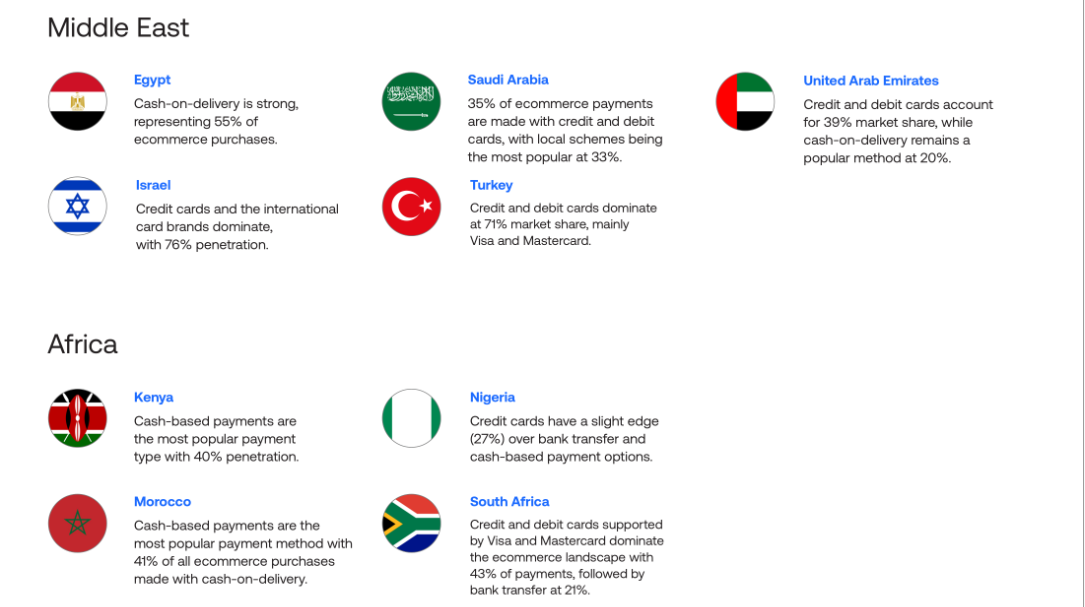 Image source: Global Payments Inc.
Businesses do need to tailor their payment choices to meet consumer demand, but most only need to select a few methods to genuinely meet their customers' needs. To identify the right mix, consider:
- Where are the majority of your customers located? Explore the most popular online payment methods in that region.
- Where do you conduct the majority of your business? If you have multiple locations, offer payment methods suited to each one.
- What platforms and devices are they using to buy? Laptop, mobile, tablet — and do they prefer digital wallets, cards, or BNPL options?
- Are you thinking of expanding into other countries? Set up the infrastructure to support the preferred payment types in that country before you launch there.
In a diverse, consumer-driven economy, ignoring payment trends is a growth risk, not just an operational gap. If you don't offer the payment methods customers want, they'll find a competitor who does.
How data translates to valuable insights
The real value isn't the data itself — it's spotting the failure before the customer does.
The most successful payments strategies are the most data-informed ones. The payments industry generates enormous volumes of data; turning it into the handful of insights that actually matter is the real work.
Those insights matter because they explain the moments that cost you customers — a declined transaction, a slow response time, a transaction timeout — and why they happened, not just that they happened.
That gap has a real cost. IR's analysis of payment failure data puts the global cost of failed payments at an estimated USD 500 billion in 2025 — roughly USD 118.5 billion in direct payment failures and USD 443 billion in false declines.
Visibility across your entire payments network — especially the customer-facing touchpoints — combined with the ability to drill into a specific anomaly and work out why it happened, is what turns that data into insight you can act on.
Analytics drive business growth
Observability turns payments data from a cost center into a growth lever.
An analytics-driven strategy reduces cost and protects revenue at the same time: spotting a processing bottleneck before it becomes a decline, or a queue backlog before it becomes a missed settlement.
Transaction volumes keep climbing, new payment methods keep emerging, and customer tolerance for a clunky checkout keeps shrinking. Keeping pace means moving from monitoring — is everything working? — to observability — why is this happening, and what should we do about it?
How IR Transact can help
One tool, full visibility, across every payment method your customers use.
Monitoring and analyzing payment transactions with IR Transact gives you visibility across your entire payments organization, through a single solution:
- Multi-vendor visibility:
monitor and manage multiple vendor solutions across on-premises and cloud deployments from one tool. - Real-time transaction visibility:
see every transaction, 24/7, as it happens. - Anomaly detection:
dynamic thresholds and alerts flag issues before they escalate. - Actionable insights:
turn transaction data into customizable dashboards your teams can act on. - Clear reporting:
translate complex data sets into representations your business and technical stakeholders can both use.
Payment preference will keep shifting as new methods launch and adoption moves between regions. The businesses that stay ahead are the ones with visibility into what's actually happening at the point of payment — not just what the roadmap assumed customers would use.
Find out more about how IR can simplify complexity using payments data
Watch the webinar