












In November 2025, SWIFT permanently retired its legacy MT messaging format. Every bank moving money across borders now operates on a single data standard, ISO 20022 — and that cutover is only the most visible piece of the biggest overhaul cross-border payments infrastructure has seen in a decade.
For years, sending money internationally meant slow settlement, unpredictable fees, and a chain of correspondent banks each taking a cut. The cross-border payments reform effort led by the G20 was built to fix exactly that. The policy progress is real. So is the gap between what regulators have promised and what payment teams experience day to day — and that gap is where the next wave of technology investment is happening.
Why cross-border payments matter now
The scale of global money movement makes even small inefficiencies expensive.
The internationalization of goods and capital markets puts cross-border payments at the center of global economic activity. Statista's 2023 analysis forecast the total value of cross-border payments worldwide would grow more than 65% by 2030, to USD 290.2 trillion, across the wholesale, B2B, and B2C segments shown below.
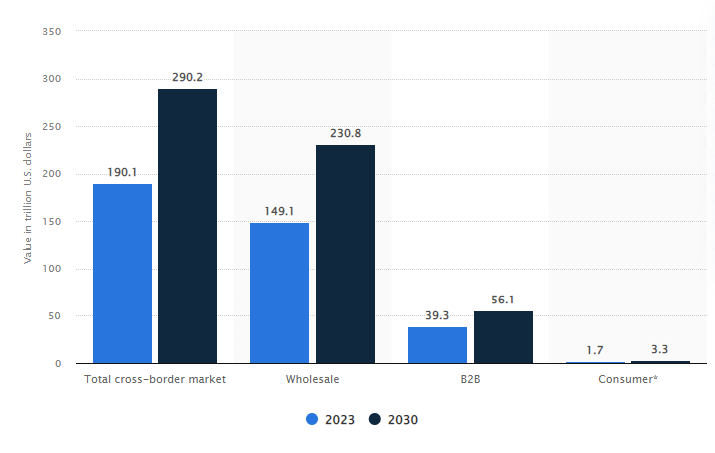
Source: Statista, 2023.
More recent research puts the trajectory even higher. Research and Markets' 2026 Global Payments Market Trends report tracks combined cross-border payment flows growing from roughly USD 190 trillion in 2024 to USD 320 trillion by 2032, with real-time cross-border transactions doubling to 575 billion over the same period. Whichever estimate proves closer, the direction is the same: volume keeps climbing, and the infrastructure underneath it has to keep pace.
Instigating change: the G20 roadmap
A single global roadmap is driving most of the progress cross-border payments has made since 2020.
Since 2020, the Roadmap for Enhancing Cross-border Payments, led by the Financial Stability Board (FSB) on behalf of G20 leaders, has driven improvements across existing and emerging payment infrastructure through 19 building blocks (BBs).
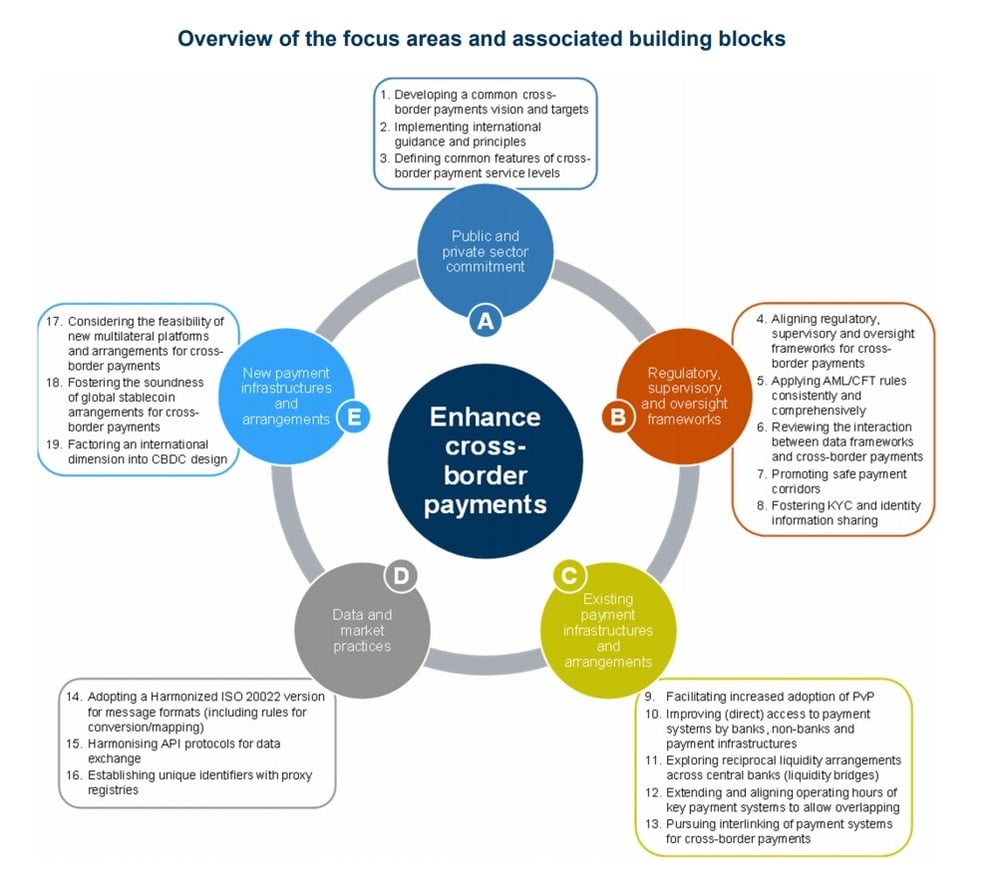
Image source: FSB
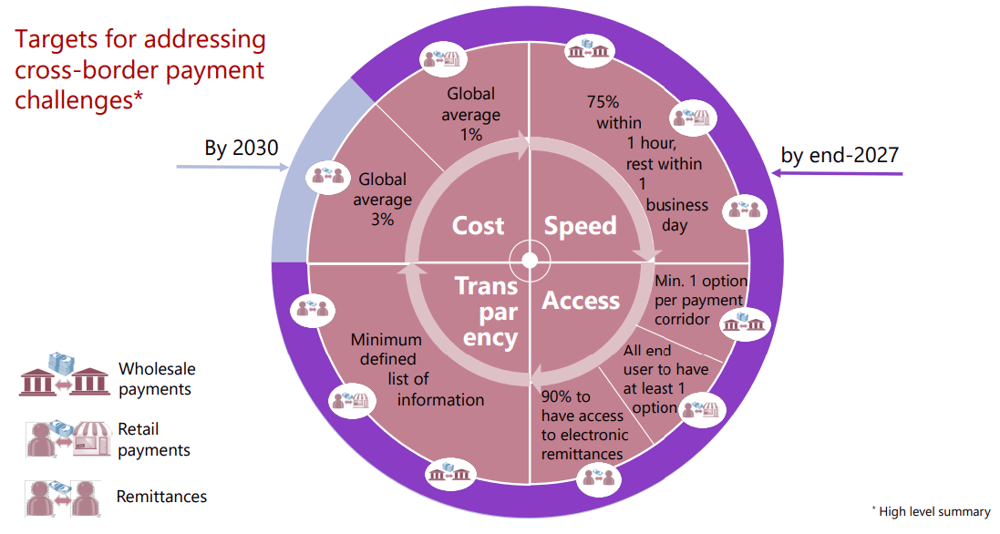
The roadmap's aim is to make cross-border payments — including remittances — faster, cheaper, more transparent, and more inclusive, without compromising safety or security. Delivered in full, it benefits banks and multinational retailers running international operations, tourists spending abroad, and migrant workers sending remittances home, while supporting broader economic growth and financial inclusion.
Four roadblocks still standing
Cost, speed, transparency, and inclusion are the same four sticking points the G20 identified in 2020.
Changes to long-standing cross-border payment processes have already shaped the stability of the international monetary system, particularly since the pandemic. But with the roadmap's end-2027 deadline approaching, the FSB's own 2025 progress report is candid about where things stand: key performance indicators have improved only slightly since 2023, and it's now unlikely the roadmap's global targets will be met on schedule. Speed has improved for wholesale payments and remittances; cost reduction and transparency for end users remain the hardest ground to gain.
Cost
Cross-border payments have always been expensive, with multiple intermediaries each charging fees, on top of foreign exchange (FX) conversion costs and varying regulatory charges. In the United States, the average cost of sending a $200 remittance has fallen to 2.8%, and to 1.9% for $500 — both under the G20's 3% ceiling. Many corridors elsewhere remain well above it, which is why cost is the target the roadmap is struggling hardest to hit globally. As international commerce keeps growing, banks and payment providers are under real pressure to offer competitive rates or lose that business to faster-moving fintechs.
Speed
Legacy technology, regulation, and market structure still make cross-border payments slower than they need to be — instructions can pass through several intermediary banks before reaching their destination, adding delay and cost at each step. Digital wallets and instant payment rails are closing that gap for same-day settlement. International accounts built on a multi-currency International Bank Account Number (IBAN) are also helping treasury teams manage cash flow, trading history, and reconciliation data in one place.
Transparency
Sending money across borders has long meant uncertainty: no visibility into transfer status, no clarity on fees until after the fact, and days spent waiting for confirmation. Regulators and international standard-setters are now pushing transparency toward becoming a global baseline rather than a differentiator.
Inclusion
Cost-effective, transparent, fast payments are part of the domestic system most developed markets take for granted — but that access remains out of reach for hundreds of millions of people and business owners making cross-border payments. One of the roadmap's explicit targets is 90% of individuals having access to an electronic instrument for sending or receiving a remittance by 2027.
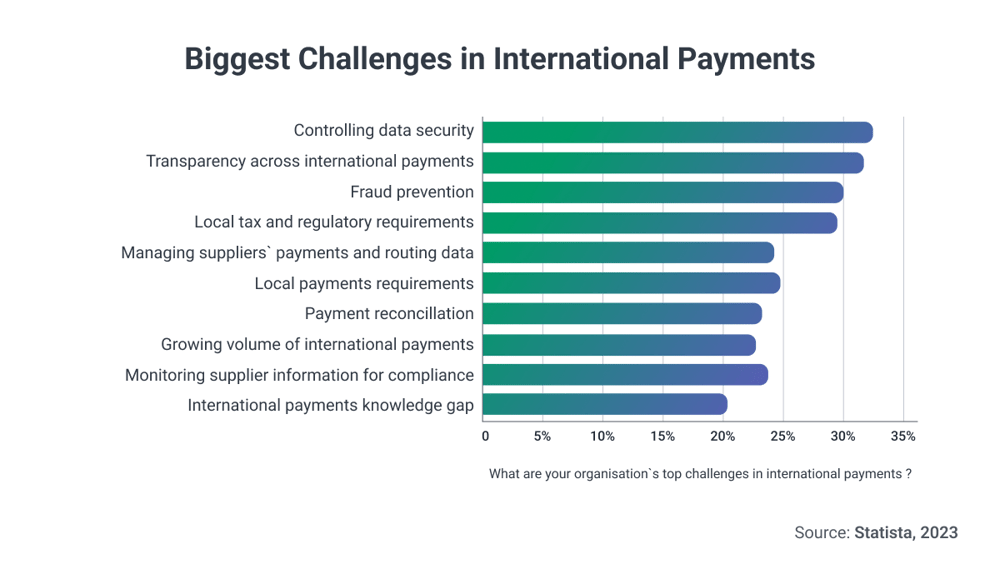
How technology is closing the gaps
A shared messaging standard, real-time FX data, and account structures that skip the need for a local bank in every market are doing most of the work.
ISO 20022: from optional to mandatory
The coexistence period between the legacy SWIFT MT standard and ISO 20022 officially ended on November 22, 2025. Every cross-border payment instruction exchanged between financial institutions on the SWIFT network must now use the ISO 20022 format; institutions still relying on MT messages risk having payments rejected outright.
For institutions still finishing their own migration, the payoff is richer, more structured payment data and real gains in operational efficiency — a driver of innovation particularly in APAC and the Middle East, where several real-time payment schemes were built ISO 20022-native from the start. For anyone operating real-time payment rails, that structured data is also what makes end-to-end monitoring possible in the first place.
Real-time FX rates with APIs
Global organizations are continually testing digital tools to optimize cross-currency workflows without disrupting existing operations. APIs have become the preferred way to do this: they plug directly into existing treasury infrastructure, giving treasurers real-time visibility into FX rates without a standalone integration project. Early access to FX rates lets organizations manage currency exposure, mitigate risk across global accounts, and reconcile faster.
Virtual accounts for wider global reach
Managing cash flow across currencies through a centralized account structure means businesses no longer need to maintain a separate local account in every market they operate in. With a centralized structure, organizations can move balances between currencies or fund local payments from one central account — maximizing liquidity and letting them operate in whichever currencies suit the business.
The regulatory landscape for cross-border payments
Compliance is getting easier to prove, not just harder to meet.
Cross-border payments regulation is complicated because it's governed by international treaties and agreements on top of national rules — which makes information-sharing between financial institutions and regulators a core part of the compliance picture. Digital identity technology is helping fintechs and challenger banks offer faster, more reliable verification, easing some of that burden.
Preventing money laundering, terrorist financing, tax evasion, and fraud remains a top priority for regulators, so anti-money laundering (AML) and know-your-customer (KYC) procedures — verifying customer identities and monitoring transactions for suspicious activity — need to be implemented and reviewed continuously. Security controls such as encryption, multi-factor authentication, and secure payment systems remain essential to preventing unauthorized access and protecting against fraud.
What's next for cross-border payments
The next wave of growth is coming from younger, mobile-first markets — not from any single new technology.
In markets like Brazil and India, younger populations who have grown up with mobile-first financial services are driving the next wave of payments innovation. In Korea, demand for alternatives to traditional wire transfers is rising fast, with consumers and businesses expecting low-cost, instant cross-border payments as the default, not the premium option. Fintech-led providers are winning share from banks precisely because they deliver on speed and transparency by default — proof that the G20's four targets are becoming competitive expectations as much as regulatory ones.
How IR Transact can help
None of this reform effort matters to a payments team that can't see its own transactions moving through it.
Faster rails, richer ISO 20022 data, and tighter regulation all raise the same operational question: can your team actually see what's happening inside its own payment flows, in real time? IR Transact, powered by Prognosis, gives payment teams that visibility across high-value, real-time, and card payment environments — from initiation through to settlement.
- Track high-value and time-critical payment flows end-to-end:
Follow a transaction's full path across the payment chain to spot delays before they become failures. - Monitor real-time and instant payment rails continuously:
Catch degraded performance or failed transactions before customers notice. - Turn transaction data into an audit-ready record:
Give compliance and AML teams the evidence trail regulators expect, without manual reconciliation.
That's the piece the G20 roadmap can't legislate into existence: an organization's own ability to prove, in real time, that its part of the system is working.
The 2027 deadline will likely arrive with some targets still unmet — the FSB says as much itself. But the bar for cross-border payments has already moved: customers, regulators, and competitors now expect real-time, verifiable, transparent money movement as the baseline, not the goal. Organizations that treat visibility into their own payment flows as core infrastructure, rather than a compliance checkbox, will meet that expectation long before it's mandatory.
See how IR Transact gives payments teams the real-time visibility the next phase of reform is built around. Get a demo.